How Much House Can You Afford in Jacksonville, FL in 2026? Real Monthly Payment Examples
How Much House Can You Afford in Jacksonville, FL in 2026? Real Monthly Payment Examples
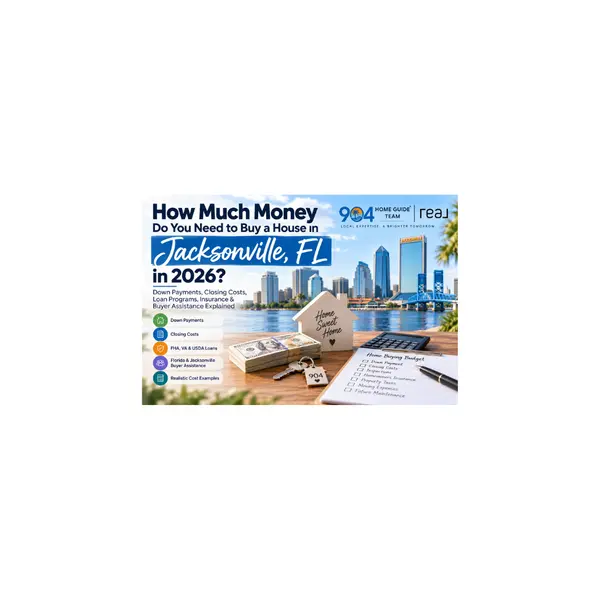
When you start looking at homes in Jacksonville, it’s easy to focus on the asking price. But a $350,000 home doesn’t come with the same monthly cost for every buyer.
Your down payment, interest rate, insurance, property taxes and loan program all affect what you’ll actually spend. Two homes listed at the same price can also have different ownership costs.
Before you build your favorites list, it helps to answer a more practical question: What monthly payment fits your life?
Start With Your Monthly Budget
A mortgage approval gives you a financing limit. Your personal budget tells you what feels manageable.
Start with your monthly take-home pay and subtract your regular expenses, savings goals and debt payments. Leave room for the things you want to keep doing after you move, whether that’s traveling, contributing to retirement or simply having a comfortable cushion.
Your housing budget should account for more than principal and interest. Property taxes, homeowners insurance and any required mortgage insurance also affect the payment. Depending on the property, HOA dues, CDD assessments and flood insurance may add to your costs.
A useful starting point is to decide on two numbers:
-
Your comfortable monthly housing budget: What you would prefer to spend.
-
Your upper limit: What you could manage while still maintaining savings and covering other priorities.
Those numbers help keep your search focused.
Jacksonville Monthly Payment Examples
The examples below show how purchase price can affect a monthly payment when the financing assumptions stay the same.
Illustrative assumptions:
-
Conventional, 30-year fixed mortgage.
-
7.40% interest rate, used for illustration only.
-
5% down payment.
-
Annual property taxes estimated at 1.2% of the purchase price.
-
Homeowners insurance estimated at $250 per month.
-
Annual private mortgage insurance estimated at 0.6% of the initial loan amount.
These are educational calculations, not mortgage quotes or estimates for a particular property. The tax percentage, insurance amount and PMI rate are placeholders, not verified Jacksonville averages.
| Purchase price | 5% down payment | Principal & interest | Taxes | Insurance | PMI | Estimated monthly total |
|---|---|---|---|---|---|---|
| $300,000 | $15,000 | $1,973 | $300 | $250 | $143 | $2,666 |
| $350,000 | $17,500 | $2,302 | $350 | $250 | $166 | $3,068 |
| $400,000 | $20,000 | $2,631 | $400 | $250 | $190 | $3,471 |
| $450,000 | $22,500 | $2,960 | $450 | $250 | $214 | $3,874 |
| $500,000 | $25,000 | $3,289 | $500 | $250 | $238 | $4,276 |
Figures are rounded independently. Totals exclude HOA dues, CDD assessments, flood insurance, maintenance, utilities and closing costs. Actual costs vary by borrower, loan and property.
Under these assumptions, moving from a $350,000 home to a $400,000 home adds approximately $403 per month. That’s why reviewing payment scenarios early can be more useful than choosing a maximum price first.
Why Two Equally Priced Homes Can Cost Different Amounts
Imagine you’re comparing two Jacksonville homes with the same asking price.
One has monthly association dues. The other has none. One has an insurance quote that fits your budget; the other costs more to insure. One needs immediate repairs, while the other has recently replaced major systems.
The purchase prices match, but the financial commitments don’t.
As you narrow your search, compare:
-
Property-specific homeowners insurance quotes.
-
Estimated property taxes for you as the new owner.
-
HOA dues and any applicable CDD assessments.
-
Flood insurance requirements and quotes.
-
Roof, HVAC and other major system conditions.
-
Immediate repairs and ongoing maintenance needs.
For taxes, use an estimate designed for a new owner rather than relying only on the seller’s current bill. The Duval County Property Appraiser offers a property tax estimator for that purpose.
Do You Need 20% Down to Buy a Home?
A 20% down payment is not required for every mortgage. Available options depend on your qualifications and the loan program.
For conventional loans, a down payment below 20% generally means private mortgage insurance is required. PMI protects the lender and adds to your borrowing costs. Your actual premium depends on factors including your credit profile and down payment.
A larger down payment reduces the amount you borrow, but it also uses more of your available cash. Ask your lender to compare options while considering how much you want left for moving, repairs and emergency savings.
Your Down Payment Isn’t Your Entire Cash Requirement
If you’re buying a $350,000 home with 5% down, the $17,500 down payment is only one part of your upfront budget.
Closing costs, prepaid items and initial escrow funding can also affect the amount you need. Your Loan Estimate shows estimated closing costs and cash to close, giving you a clearer picture of the funds required to complete the purchase.
Also plan for expenses outside closing, such as inspections, moving and anything the home needs before you settle in.
How to Build a More Useful Home Search
Before touring homes, take these steps:
-
Choose a comfortable monthly budget. Include room for savings and ongoing ownership expenses.
-
Speak with a lender. Review financing options and the cash each would require.
-
Build a search around that budget. Account for property-specific costs as you compare listings.
-
Get updated estimates on your favorites. Replace general assumptions with actual insurance quotes, tax estimates and community fees.
You don’t need every answer before you begin. You do need a process that makes the numbers clearer as you move forward.
Planning to Buy a Home in Jacksonville?
Michael William Rolewicz with Real Broker LLC can help you compare Jacksonville homes, understand the differences between properties and coordinate with your lender as you build your budget.
Reach out to Mike to start a home search around your price range, monthly payment goals and priorities.
Payment examples are for educational purposes only. The illustrative interest rate is not an advertised offer or statement of current rates. Obtain personalized financing terms and property-specific cost estimates before making a purchase decision.
Categories
Recent Posts